

For many homebuyers, saving for a down payment is one of the biggest hurdles to homeownership. And if you’ve heard that you need 20% down to buy a home, the goal can feel especially difficult.
The good news is that a 20% down payment isn’t always required. Some conventional mortgage programs allow qualified buyers to purchase a home with much less upfront. The tradeoff is that putting less than 20% down often means paying private mortgage insurance, commonly known as PMI.
PMI adds to the cost of a mortgage, but it can give buyers another path to homeownership. Understanding how it works can help you decide how PMI fits into your homebuying strategy.
What is Private Mortgage Insurance?
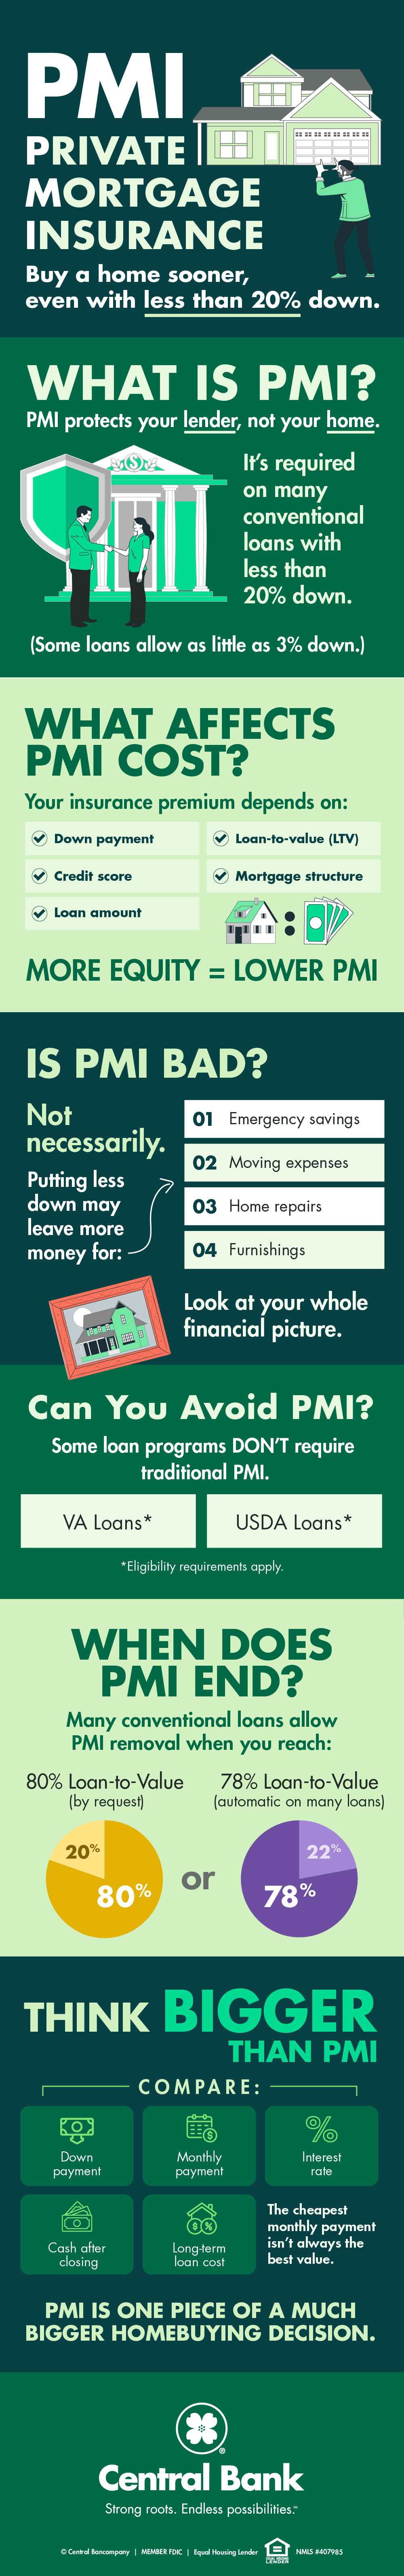
Private mortgage insurance is insurance that protects your mortgage lender if you stop making payments on your loan. It is commonly required on conventional mortgages when a homebuyer makes a down payment of less than 20%.
PMI should not be confused with homeowners insurance. Homeowners insurance provides financial protection for your home and belongings against certain covered losses. PMI protects the lender rather than the homeowner.
PMI should not be confused with homeowners insurance. Homeowners insurance provides financial protection for your home and belongings against certain covered losses. PMI protects the lender rather than the homeowner.
For buyers still getting familiar with terms like principal, interest, taxes and insurance, understanding the different components of a mortgage can make it easier to see where PMI fits into the overall cost of a home loan.
The key benefit of PMI is straightforward: It can allow qualified buyers to purchase a home without accumulating a full 20% down payment first. Some conventional loan programs may permit down payments as low as 3%.
How Does PMI Work
You typically don’t shop for PMI separately from your mortgage. Your lender arranges the coverage as part of the loan process. Monthly borrower-paid PMI is one of the most common arrangements. In this case, the PMI premium becomes part of your monthly mortgage payment. Your total housing payment may include principal, interest, property taxes, homeowners insurance and PMI.
Other structures may include an upfront premium or lender-paid mortgage insurance. With lender-paid PMI, you may not see a separate monthly PMI charge. The cost can instead be reflected in a higher mortgage interest rate.
That distinction matters when comparing loans. A mortgage without a separate PMI charge is not necessarily less expensive than one with monthly PMI. Comparing the interest rate, monthly payment, upfront costs and total borrowing costs can provide a clearer picture.
When you’re preparing to apply for a mortgage, a mortgage checklist can help you gather the financial information and documentation you may need during the process.
How Much Does PMI Cost
There is no universal PMI rate. Your cost is based on your mortgage and borrower profile.
Factors that can affect your PMI premium include:
- Down Payment: A larger down payment reduces the amount you need to borrow and your loan-to-value ratio.
- Loan-to-Value Ratio : This compares the amount you owe on your mortgage with the value of the property.
- Credit Score
- Loan Amount : Since PMI is tied to the amount borrowed, the size of your mortgage can affect your premium.
- Mortgage Structure : Different loan and mortgage insurance arrangements can produce different costs.
PMI is typically calculated as a percentage of the loan amount, with several borrower and loan characteristics affecting the final premium.
Instead of evaluating PMI on its own, look at how it affects your complete mortgage payment. A lender can help you compare different down payment amounts and loan structures to see how each option changes both your upfront costs and monthly payment.
Is PMI a Bad Thing?
It is easy to think of PMI as a fee that should always be avoided. From a financial planning standpoint, the answer can be more nuanced.
Putting 20% down on a conventional mortgage can eliminate the need for PMI from the beginning. It means bringing considerably more cash to the closing table.
Putting less down may leave a buyer with more savings available after the purchase. Those funds could be needed for moving costs, repairs, furnishings, emergency savings or other financial priorities.
PMI comes with a cost, so buyers should understand exactly what they will pay. Its presence alone does not tell you whether a mortgage is a good or bad choice.
Think about PMI within your broader homebuying budget. Compare how different down payments affect the amount you borrow, monthly payment, available savings and expected PMI costs. Looking at the full financial picture can be more useful than making 20% down the goal for every purchase.
Can You Avoid PMI With Less Than 20% Down?
Traditional PMI is associated with conventional mortgages, so different loan programs may have different insurance requirements.
For example, eligible borrowers may have access to VA loans, which do not require traditional PMI. USDA loans do not use conventional PMI either, though they have their own guarantee fees and eligibility requirements.
Some conventional lenders may offer lender-paid mortgage insurance. In this arrangement, the lender pays the mortgage insurance premium, with the cost commonly reflected elsewhere in the loan, such as the interest rate.
The absence of a monthly PMI line item does not mean there is no cost associated with the alternative. Depending on the mortgage, borrowers could encounter a higher interest rate, upfront fee or another form of mortgage insurance.
When comparing your options, look beyond whether a loan has PMI. Consider the total monthly payment, upfront expenses, interest rate, loan terms and long-term borrowing costs.
When Can PMI Be Removed?
One advantage of PMI on many conventional mortgages is that it does not necessarily remain for the life of the loan.
Under federal law, many homeowners can request PMI cancellation when their mortgage principal balance is scheduled to reach 80% of the home’s original value. Borrowers who make additional principal payments may be able to request cancellation earlier once their balance reaches that threshold.
A cancellation request may require you to:
- Make the request in writing
- Have a good payment history
- Be current on your mortgage
- Show that there are no junior liens on the property
- Provide evidence that the home’s value has not fallen below its original value if requested
PMI generally must be automatically terminated when the mortgage is scheduled to reach 78% of the home’s original value, provided the borrower is current on payments. Different requirements can apply to certain mortgages, so check with your loan servicer about the rules for your loan.
PMI generally must be automatically terminated when the mortgage is scheduled to reach 78% of the home’s original value, provided the borrower is current on payments. Different requirements can apply to certain mortgages, so check with your loan servicer about the rules for your loan.
Understanding how home equity works can help you track the relationship between your home’s value and the amount you still owe
Making PMI Part of Your Homebuying Decision
PMI is only one piece of a much larger mortgage decision. Rather than asking only how to avoid PMI, consider what different down payment and mortgage options mean for your finances.
Look at the cash you will need upfront, your complete monthly housing payment, how much savings you will have after closing and the long-term cost of the loan. Ask your lender to show you how different down payment amounts affect PMI, interest rates and monthly payments before choosing a mortgage structure.
Buying a home involves much more than reaching a particular down payment percentage. Continue building your homebuying knowledge with Central Bank’s homeownership resources, where you can explore guidance on mortgages, home equity and managing the financial responsibilities that come with owning a home.
